A pre qualification is a quick estimate based on what you tell a lender, without verifying your income, assets or credit, so it carries little weight with sellers. A pre approval means the lender has checked your credit and reviewed your documents, which makes your offer far more credible. The strongest position is a fully underwritten approval, where everything except the specific house has been cleared. Get pre approved before you tour, and keep your finances steady until closing.
Pre approval and pre qualification are often used interchangeably, but they're genuinely different, and understanding the distinction can matter a great deal when you're competing for a home in Chandler.
I was a loan officer before I became a broker, so I've seen both sides of this. Here's the plain version.
What pre qualification actually means
Pre qualification is typically a quick, informal estimate based on self reported financial information, without full verification of income, assets, or credit. It's a helpful starting point but carries little weight with sellers.
Pre qualification still has a place. It's a quick way to see whether homeownership is in reach and roughly what range to think about, before you gather every document. Just don't send it with an offer and expect it to carry weight, and don't plan your search around a number nobody has checked.
What pre approval actually means
Pre approval involves your lender actually verifying your income, assets, and credit, resulting in a much stronger, more reliable estimate of what you can borrow. This carries real weight with sellers evaluating competing offers.
Ask your lender which parts of your file were actually reviewed by a person, and which were only entered into a system. The more that's been reviewed, the fewer surprises later.
Full underwriting: the strongest position
Beyond standard pre approval, some buyers go through full underwriting before house hunting, essentially clearing every part of their loan except the specific property. This is the strongest possible position in a competitive offer.
| Pre qualification | Pre approval | Fully underwritten | |
|---|---|---|---|
| Credit checked | Usually not | Yes | Yes |
| Income and assets verified | No | Reviewed | Reviewed by underwriting |
| Weight with sellers | Little | Strong | Strongest |
| What's left | Everything | Final underwriting and the property | Mostly the property |
Why this distinction matters in a competitive offer
In any multiple offer situation, a seller comparing offers will view a fully verified pre approval as far more credible than a basic pre qualification, it signals your financing is much less likely to fall through. See How do you win a multiple offer situation in Chandler, AZ?
What lenders usually ask for
Expect to provide recent pay stubs, W-2s or tax returns, bank and investment statements, and permission to pull your credit. If you're self employed, receive gift money for the down payment or have income from support or a second job, tell the lender up front.
What a good pre approval letter shows
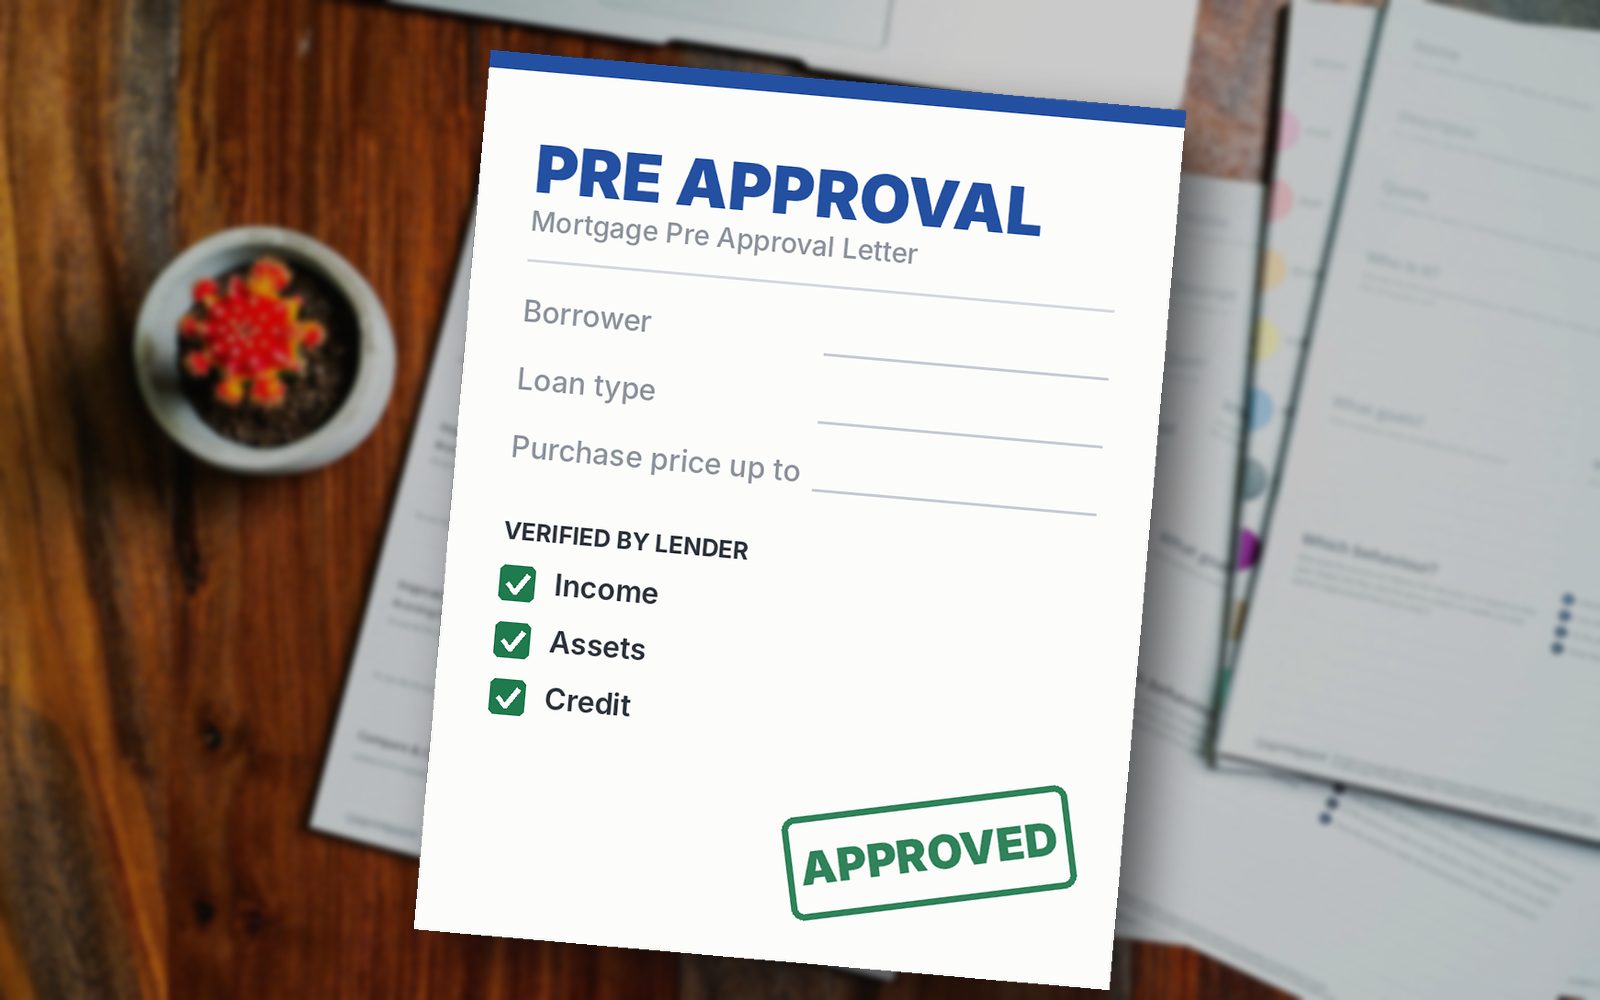
Not every letter is equal. A strong one names the loan type, the loan amount or price it supports, the down payment it assumes, what was verified and when it expires. When we write an offer, I'll ask your lender for a letter matched to that specific offer price, so a seller doesn't see a much higher number than you're offering and assume there's more room.
How long it's good for
A pre approval doesn't last forever. Credit reports, pay stubs and bank statements go stale, and lenders usually want fresh copies after a few months. If your search runs longer than expected, ask your lender to update it before you write an offer, not after the seller's agent asks.
Shopping more than one lender
You can compare lenders without wrecking your credit. Credit scoring models generally treat several mortgage credit checks made within a short window as a single inquiry, so do your comparing in a focused stretch. After you apply, each lender has to give you a Loan Estimate within three business days. That standard form makes it easy to compare rates, fees and cash to close side by side.
Keep it valid until closing
A pre approval isn't a promise. Final approval still depends on the appraisal and on nothing big changing. Don't open new credit, finance furniture, change jobs or move large sums of money around without talking to your lender first.
If you're self employed
Self employed buyers can absolutely get pre approved, it just takes more paperwork. Lenders usually want two years of personal and business tax returns, and they qualify you on what's on those returns after business deductions, not on your gross revenue. If you write off a lot, your qualifying income may be lower than you expect. As a CPA, I'd have that conversation with your lender and your tax preparer before you file, not after.
How I help you get properly positioned
Before we start touring homes, I make sure you understand exactly where you stand, connecting you with a lender who will give you a real, verified pre approval, not just a quick estimate that won't hold up when it matters. Then we work out your comfortable number in How much home can you comfortably afford in Arizona?
The bottom line
Before you tour a single home, let's make sure you're properly positioned with a real pre approval, not just an estimate.
Let's take the confusion out of this decision, schedule your clarity call today.
Questions, answered.
Is pre qualification enough to start touring homes?
It can be a starting point, but I recommend moving to full pre approval before making any offers, especially in a competitive situation.
How long does pre approval typically take?
It varies by lender, but often just a few days once you've provided the necessary documentation.
Does pre approval guarantee my loan will close?
Not entirely, final approval still depends on the specific property, through the appraisal, and no major changes to your finances during the process, but it's a much stronger indicator than pre qualification alone.
How long is a pre approval good for?
Often around 60 to 90 days, depending on the lender. Ask what they'll need to refresh it.
Does getting pre approved hurt my credit?
A credit check can have a small effect. Shopping with several lenders within a short window is generally treated as one inquiry for scoring, but ask your lender.
Want to talk it through?
Bring me the specifics of your situation and I will tell you straight what I would do. No pitch, nothing to sign, and no obligation to work with me afterward.
Get properly positioned